I Am Selling! Why Would I Put Money into a House I am Leaving?
I would say this is the most frequently occurring questions professional stagers field every day! On the surface you can certainly understand why the question is raised repeatedly. There are many reasons to support the process of staging a property prior to bringing it to the public for review. Let’s look at a few of them.
read more
Manual vs. Automated Underwriting
There are different types of underwriting. Underwriting, which is making certain the loan complies with the guidelines for which the loan is for, can be a thorough review or it can be a quick ‘drive through’ type where the loan application gets less scrutiny. What are the differences and why do lenders do both?
read more
RE/MAX National Housing Report
More Inventory Gave Homebuyers Added Options as Prices Held Steady in July
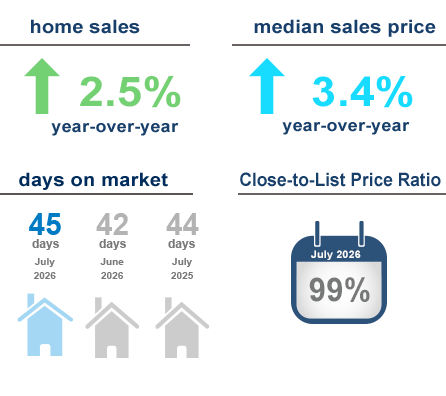
read the full report
If You Have the Option of Putting More Money Down, Should You?
With the exception of the VA and USDA programs, along with certain down payment assistance programs, almost every residential loan program does indeed require some sort of down payment. Many borrowers want to come to the closing table with as little cash as possible, and as the down payment amount is the largest chunk of change needed, the lowest down payment is often the request.
read more
Can You Borrow Your Downpayment?
Sounds like a silly question at first, but can you borrow money for your downpayment? In general, the answer is no. Your funds needed for your down payment, closing costs, and cash reserves need to come from an account you own such as a checking or savings account with your name on it. Lenders will need to verify not only the existence of these funds, but that they belong to you, and you have access to them.
read more
Corvallis Market Conditions
Shape of the Current Market: Summer/Fall 2026
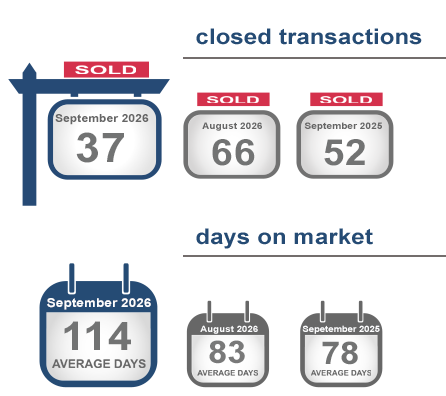
September Real Estate Roundup
"The housing market remains supported by a solid labor market and an economy that is growing at a healthy rate."
30-year fixed-rate mortgage (FRM) averaged 7.03 percent for the week ending September 24, 2026, up from last month when it averaged 6.66 percent. A year ago, at this time, the 30-year FRM averaged 6.30 percent.
learn more